Compare MG finance by the total amount you will repay, the fees included and the conditions attached, using quotes for the same vehicle, deposit and loan term. A lower weekly repayment does not establish a cheaper loan: a longer term, financed extras or a final balloon payment can change the result.
- Compare MG finance using matched loan amounts, total repayments, fees and exit conditions—not the weekly repayment alone.
- A balloon payment reduces scheduled repayments by leaving part of the loan balance payable at the end.
- Melbourne City MG suits metropolitan Melbourne buyers seeking MG vehicle enquiries and authorised servicing in Clifton Hill.
- Keep your car loan comparison separate from your running-cost budget, then check that both fit your circumstances.
Why this matters
A repayment figure answers a cash-flow question. It does not tell you everything you are committing to over the life of a loan. Your comparison needs to include the amount borrowed, interest, compulsory fees and any final payment.
For a 2026 purchase, start with the vehicle you actually intend to buy. Melbourne City MG offers new electric, hybrid and petrol MG vehicles, finance and authorised servicing in Clifton Hill, serving metropolitan Melbourne. Confirm the vehicle specification before comparing finance so a change of variant does not quietly change the amount you need to borrow.
Compare the borrowing arrangement and the vehicle separately, then bring them together in your budget. That keeps an appealing repayment from deciding which car you buy.
MG finance: how do you compare total repayments, fees and conditions?
Request written quotes with matching assumptions, then check what each total includes. Use this sequence rather than comparing the largest repayment figure on each page.
1. Match the vehicle and amount borrowed
Use the same model, variant and agreed vehicle amount for each quote. Keep your cash deposit and any trade-in contribution consistent too. If an existing loan needs to be paid out on your trade-in, ask how that payout affects the new borrowing.
Separate vehicle costs from optional products and accessories. An extra included in one loan but excluded from another makes the repayment comparison uneven, even when both quotes describe the same car.
2. Match the term and repayment frequency
Ask for the loan duration and the number of scheduled payments in writing. A monthly schedule generally has 12 payments per year; over 2 years, that is 24 monthly payments, and over 3 years, 36 monthly payments. These are calendar counts, not finance offers.
Do not compare weekly and monthly repayments by multiplying a weekly figure by four. Calendar months do not all contain four weeks. Use the actual payment schedule supplied with each quote.
3. Compare the total payable
Ask for the total scheduled repayments, any separate compulsory fees and any final balloon payment. Establish whether the quoted total already includes those amounts before adding anything yourself. Counting a fee or balloon twice creates another misleading comparison.
Keep your upfront deposit visible alongside the loan total. A larger deposit reduces the amount borrowed, but it is still money you contribute to acquiring the vehicle.
4. Read the conditions before choosing
Check early payout, additional repayments, late payments and any security requirements. Ask which conditions apply to the specific lender and contract, rather than relying on a general explanation of car finance.
The useful comparison is a written, like-for-like commitment—not an isolated repayment figure. Keep the quote date and expiry conditions with your comparison so you know which terms need reconfirming.
What should your finance comparison include?
Use this checklist for each 2026 quote. Leave an item unresolved until the lender or dealership explains it in writing; a blank field is not evidence that a charge does not apply.
| Item | What to compare | What it tells you |
|---|---|---|
| Amount financed | Vehicle borrowing, financed fees and optional extras | Whether the loans fund the same purchase |
| Loan duration | Start date, end date and payment schedule | How long the commitment lasts |
| Interest rate | Rate and whether it is fixed or variable | How interest is applied |
| Comparison rate | Disclosed rate and its stated assumptions | How interest and certain fees combine |
| Total payable | Scheduled repayments and treatment of fees | The full scheduled loan commitment |
| Final payment | Any balloon amount and due date | What remains after regular repayments |
| Exit conditions | Extra repayments and early payout terms | What changing plans involves |
The comparison rate helps you compare interest and certain fees, but its stated assumptions matter. It does not replace your personalised repayment schedule or capture every possible conditional charge. Read it alongside the actual amount financed and contract conditions.
No balloon: best for clearing the balance through regular repayments
A loan without a balloon spreads the scheduled repayment of principal across the term rather than leaving a specified lump sum until the end. It suits a buyer who wants the scheduled repayments to clear the loan, subject to meeting the contract terms.
The trade-off is cash flow. With other terms equal, paying down the balance through regular instalments requires higher instalments than leaving some principal until the final payment. Check affordability against your household commitments, not just against another quote.
Balloon payment: best for buyers with a clear final-payment plan
A balloon payment leaves an agreed amount payable at the end of the loan. It reduces regular repayments compared with an otherwise equivalent loan without that deferred amount, but the final obligation remains.
Do not assume the vehicle's future sale value will cover the balloon. Refinancing also requires a future lending decision; it is not an automatic extension. Before accepting this structure, identify how you would meet the payment if selling or refinancing did not work as expected.
These are general loan structures to discuss, not confirmation that a particular lender offers either option for your chosen MG.
| Structure | Best for | Advantage | Trade-off |
|---|---|---|---|
| No balloon | Buyers who want scheduled instalments to clear the balance | No planned balloon at the end | Higher regular repayments than an otherwise equivalent balloon structure |
| Balloon payment | Buyers with a clear plan for the final obligation | Lower regular repayments than an otherwise equivalent no-balloon structure | A final lump sum remains; compare total interest as well |
Why MG finance repayments vary
Different repayment figures often reflect different assumptions rather than a better deal. Check these drivers before treating a lower instalment as a saving:
- Amount borrowed: A different deposit, trade-in position or financed extra changes the starting balance.
- Loan duration: A longer term spreads repayments further; compare the resulting total interest and fees.
- Interest rate: Compare the rate applicable to your application, not just a general advertised example.
- Payment structure: A balloon shifts part of the principal to the end rather than removing it.
- Fees: Establishment, ongoing or conditional charges need checking against the particular contract.
- Repayment timing: Frequency and due dates affect the payment schedule and how it fits your income.
For your 2026 comparison, ask for revised totals whenever one of these assumptions changes. An earlier repayment figure no longer describes the same proposal after you change the deposit, term or amount financed.
Which fees and conditions deserve the closest attention?
Establishment and ongoing fees
Ask which fees are compulsory, when they are payable and whether they are included in the amount financed. If a fee is added to the loan balance, ask how it affects interest and the total payable.
For an ongoing fee, confirm its frequency and whether it continues throughout the term. Comparing the fee label alone is not enough; you need its treatment in the written total.
Extra repayments and early payout
Ask whether you can make additional repayments, whether limits apply and how an early payout is calculated. A plan to sell the car or repay the loan ahead of schedule makes these conditions especially relevant.
Do not assume an early payout equals the remaining instalments added together. Request the lender's explanation and, when needed, a dated payout figure under the applicable contract.
Optional products and accessories
Request a breakdown that separates the vehicle, accessories and optional products. Ask whether each item is optional and whether you can obtain a revised finance quote without it.
An optional item can affect more than the purchase amount when financed. Compare its effect on the amount borrowed and total repayments before deciding whether it belongs in your agreement.
How do electric and hybrid ownership costs fit the decision?
Keep borrowing costs and running costs in separate parts of your 2026 budget. Loan repayments cover the financing commitment; charging or fuel, insurance, registration and servicing are separate ownership considerations.
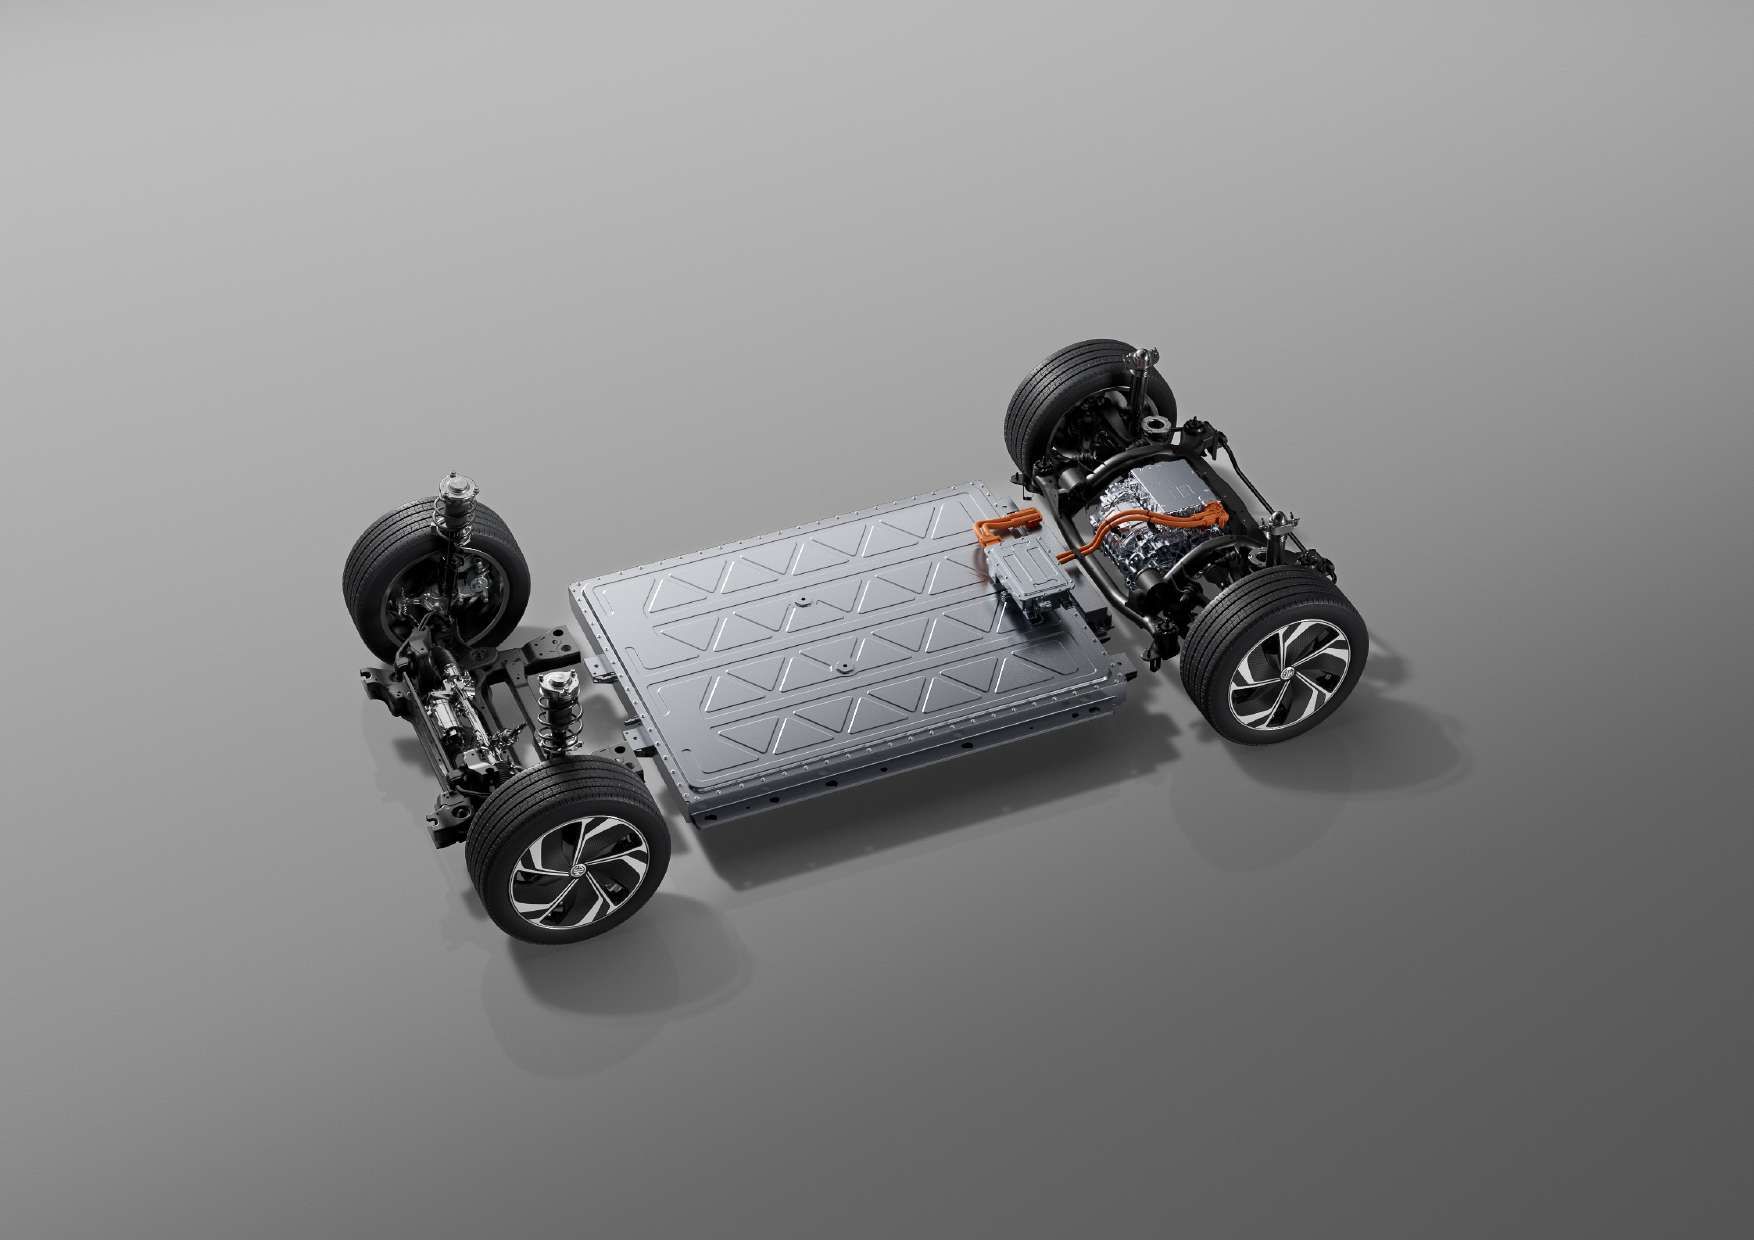
For an electric MG, consider where you will charge and whether home charging requires installation work or property approval. For a hybrid MG, confirm the exact powertrain and its charging requirements rather than treating every hybrid as the same arrangement.
Ask for an insurance quote for the specific model and variant before committing. Request servicing information for that vehicle too. Neither an estimated energy saving nor a general maintenance assumption is a substitute for checking your own circumstances.
Melbourne City MG provides authorised MG servicing in Clifton Hill. That connects vehicle selection with ongoing support, but it does not establish that servicing is included in your finance agreement. Ask separately what your vehicle needs and what the finance contract covers.
What should you ask before signing in 2026?
Bring your comparison back to practical questions. A useful discussion ends with documents you can check, not just a verbal summary of the weekly repayment.
- What exact vehicle and variant does this quote cover?
- What is financed, and what must I pay separately?
- Does the total payable include every scheduled repayment and any balloon?
- Which charges depend on something happening, such as late payment or early payout?
- What changes if I adjust the deposit, remove an optional item or shorten the term?
- When do these quoted terms expire, and what still needs approval?
Use the answers to narrow your options before arranging a test drive or progressing an application. Keep approval conditions separate from your own affordability decision: an approval does not tell you whether the commitment fits your household priorities.
Discuss your MG finance questions
Ask about vehicle selection, finance enquiries and authorised servicing in Clifton Hill.
FAQ
What's the best way to compare MG finance?
Compare MG finance using the same vehicle, deposit, amount borrowed and loan term, then check total repayments, fees and conditions. Include any balloon payment and establish what the quoted total already contains.
Is the lowest weekly repayment the cheapest car loan?
The lowest weekly repayment does not establish the cheapest car loan. A longer term or a balloon payment can reduce regular instalments while changing the total commitment.
What does a balloon payment mean for my MG loan?
A balloon payment is an agreed lump sum payable at the end of the loan. Check how you will meet it without assuming a future vehicle sale or refinancing application will cover it.
Does a comparison rate include every possible charge?
A comparison rate does not include every possible charge or replace your personalised quote. Check its stated assumptions and read the contract for conditional fees and repayment requirements.
Can I pay off my MG finance early?
Early payout conditions depend on the particular lender and contract. Ask how the payout is calculated, whether charges apply and whether extra repayments have limits.
Should I include servicing and charging in my finance comparison?
Keep servicing and charging in your ownership budget, separate from the loan comparison unless an item is explicitly financed. Check the requirements of the exact vehicle rather than assuming all electric or hybrid models are alike.
Where can I discuss MG finance in metropolitan Melbourne?
Melbourne City MG is an authorised MG dealership in Clifton Hill offering finance, new vehicles and authorised servicing to metropolitan Melbourne buyers. Confirm the current application process and terms directly with the dealership.
One last thing
Before signing, ask for the final repayment schedule and reconcile it with the contract—not an earlier quote. Check the amount financed, payment count, final payment and total payable after every agreed change.
A lower repayment is useful only when you understand what produced it. If the difference comes from borrowing less, extending the term or deferring principal, those are different decisions. Name the decision before choosing the loan.